Payment tracking and collections for consumer lenders
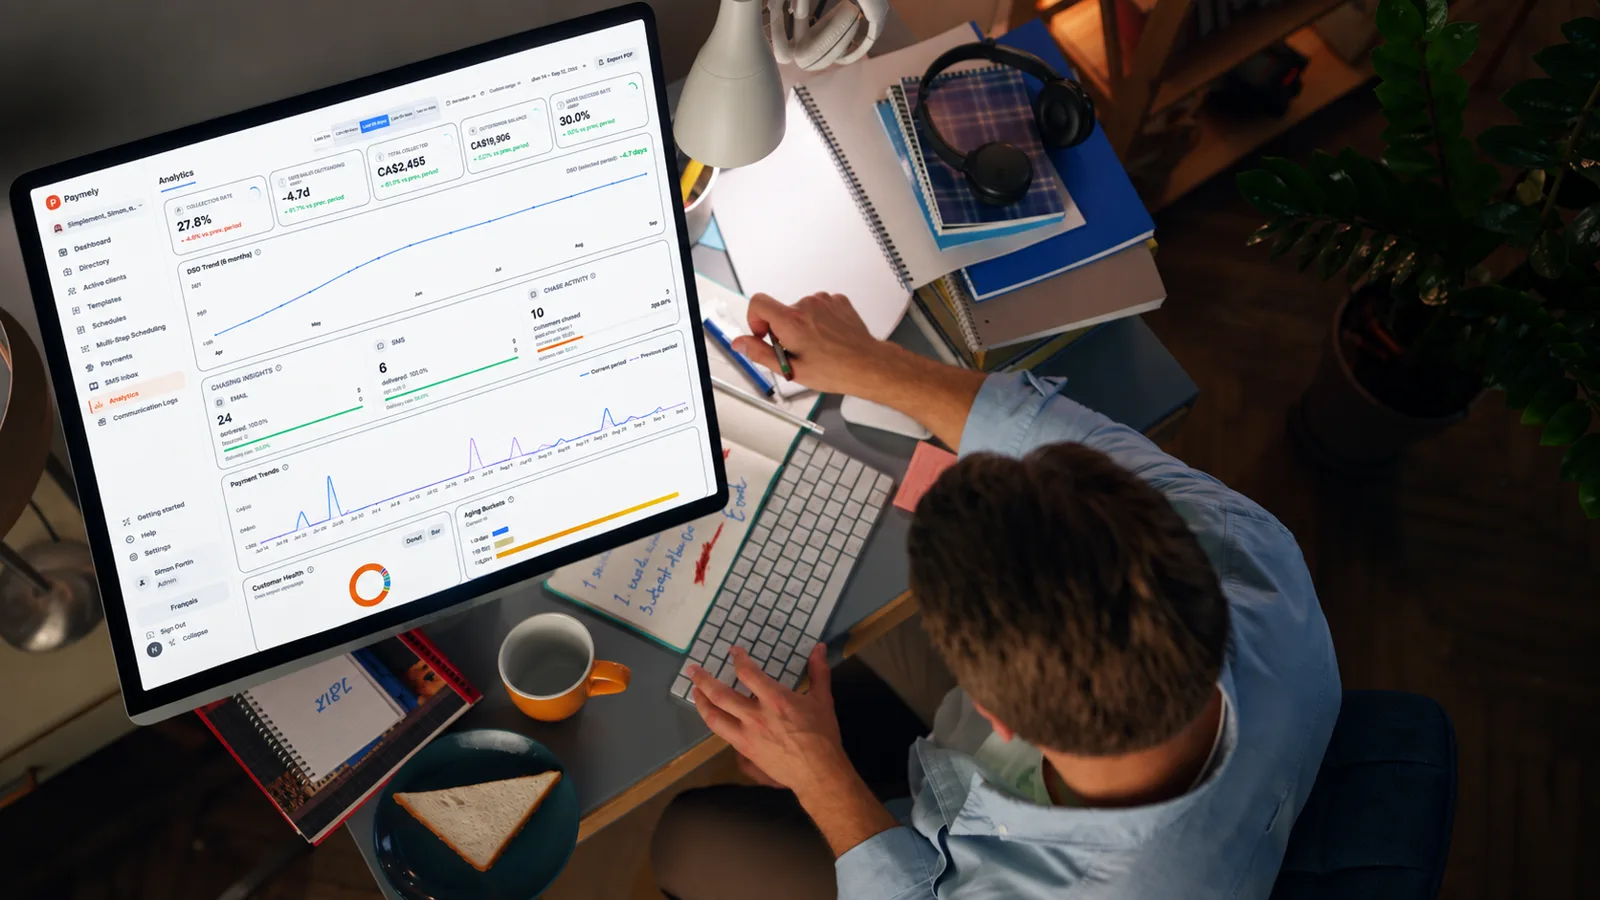
Payment schedules, recurring instalments and reminders before the due date. Every borrower is followed up automatically by email and SMS. And when someone needs to talk, the call happens inside Paymely with our virtual phone: your team calls in one click from the browser, or lets the AI do it, in French or English.
- Personal loans
- Microcredit
- Purchase financing
Paymely is Quebec-built automated collections software, designed for consumer lenders.
Industry challenges
More loans, tighter budgets and two laws to follow
Every loan means dozens of due dates. A late payment nobody follows up becomes two. And every manual call to catch up has to respect the tone, hours and record-keeping the law requires.
What the borrower receives
Three messages, one transfer, zero calls
Example for a $312.50 monthly instalment. Amounts and dates come from your file; the tone comes from your templates.
Hi Marc, a quick reminder: your $312.50 instalment is due on the 15th. Thank you!
[Your company]: your $312.50 instalment is due today. Reply to this message with any questions.
Hi Marc, your instalment from the 15th is still unpaid. One Interac transfer to payments@… and you're all set.
Interac transfer spotted · $312.50 · approved by your team
Everything in one place
What does Paymely do for a lender?
Reminder before the due date
A courteous email or text a few days before each instalment.
One file per instalment
A late instalment doesn't affect the others.
Interac transfers spotted by AI
Shown to your team, approved in one click, follow-up stopped.
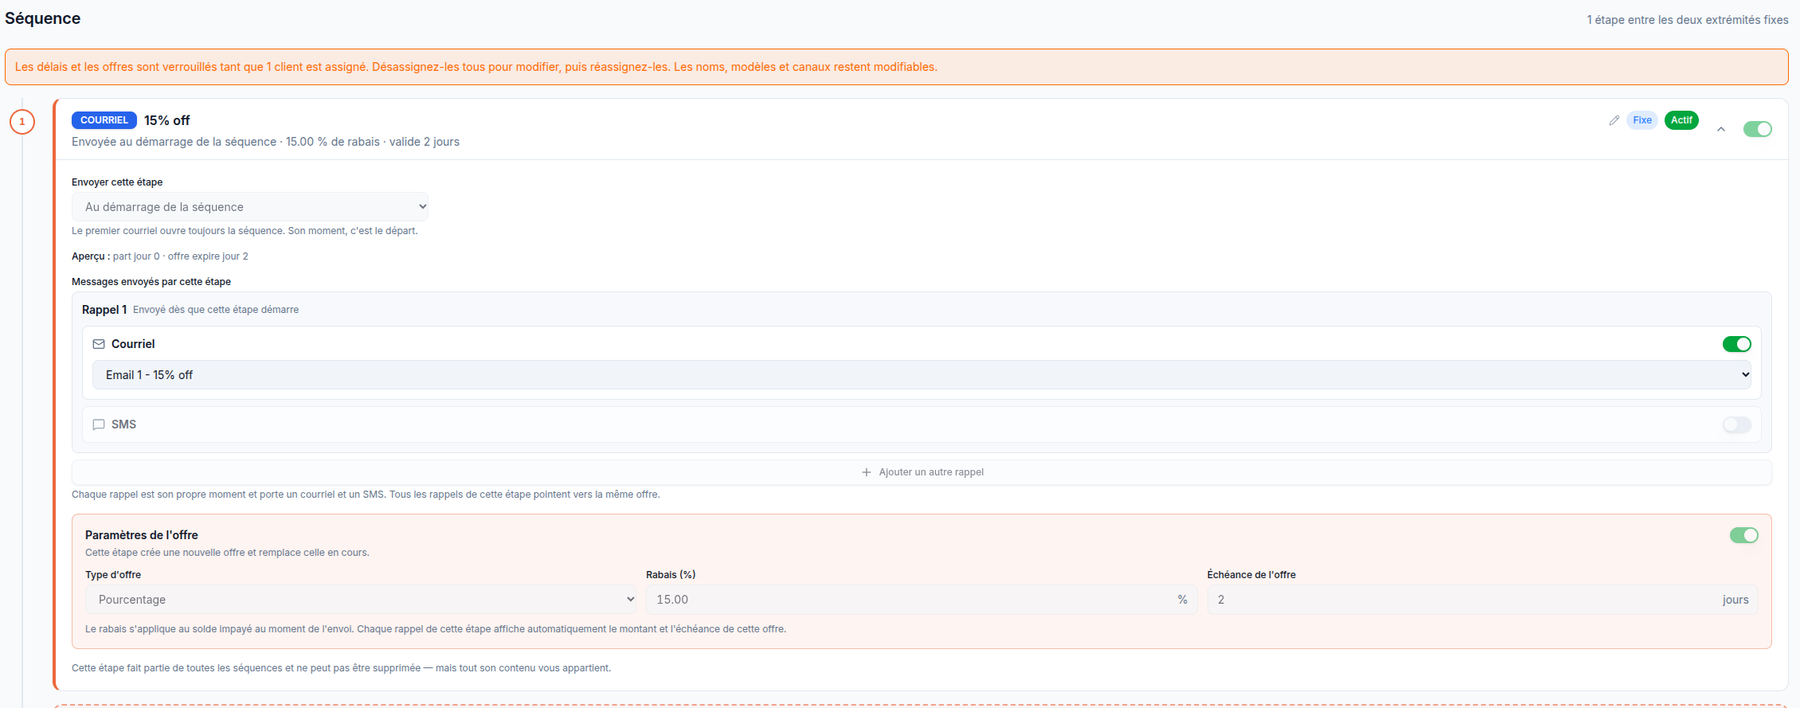
Escalating reminders and settlement offers
The tone rises step by step; the payment plan offer goes out according to your rules.
SMS inbox
Borrowers reply by text, and you see everything on their profile.
Virtual phone
Call from your browser in one click on the profile: nothing to install. The recording, notes and call time stay on the file.
AI voice calls, in French and English
The AI calls the borrower for you and explains their balance. The outcome, recording included, is logged on their profile. You choose who it calls, and when.
Three choices that matter
Why Paymely instead of an invoicing tool?
- 01
No payment without human approval
The AI suggests, your team decides. No file is settled without your click.
- 02
Built for payment schedules
Recurring templates, due-date and balance tags, one sequence per loan type.
- 03
Quebec, Law 25, debt collection rules
Canadian hosting, permitted hours, unsubscribe by replying STOP, a log of every exchange.
What the research says
SMS reminders work, and your borrowers ask for them
Paymely publishes no customer performance statistics. Sources at the bottom of the page.
Frequently asked questions
Does Paymely handle loans with multiple instalments?
Yes. That's exactly what the “recurring payments” category does. You import the payment schedule and Paymely tracks every date.
What happens when a borrower pays late?
The reminder sequence starts the day after the due date, with the timing and tone you set once per loan type.
How does the AI spot an Interac transfer?
It reads the transfer notice, matches it to the borrower and the expected amount, and shows it to you. Nothing is applied without your approval.
Can I offer a payment plan automatically?
Yes. Percentage, timing and expiry are your rules; the offer goes out at the step you choose.
How long before we're up and running?
One import file and a guided onboarding session. No IT project.
Does it comply with Law 25 and Quebec's debt collection act?
Paymely provides the guardrails and the audit trail. The content of your messages remains your responsibility, and we help you write it.
Sources
Updated September 13, 2026
- Equifax Canada, “Non-Mortgage Delinquency Growth Slows in Second Quarter,” August 24, 2026.
- Statistics Canada, National balance sheet accounts, second quarter 2026.
- Commission d'accès à l'information du Québec, Administrative monetary penalties (Law 25).
- Barboni, G., Cárdenas, J. C. and de Roux, N., “Behavioral messages and debt repayment,” Review of Finance, 2026.
- Burlando, A., Kuhn, M. A., Prina, S. and Wilson, B. M., “Helping Borrowers Recover from Loan Default: Evidence from Digital Credit,” Innovations for Poverty Action, 2025.
- Datos Insights for Solutions by Text, survey of 1,500 borrowers, November 2025.
- TransUnion, “Preparing for Opportunity: Investing in Efficiency to Scale Operations,” January 2025.
Tell us how your loans work.
We'll show you, on your own payment schedules, what your borrowers would receive.